Menu
Date Published: September 2, 2026 (Updated October 30, 2026)
Table of contents :
Yes. Pension income can qualify as income for a payday loan in Canada. What matters is that the money comes into your bank account regularly. Government pensions such as Old Age Security (OAS), and workplace or private pensions, can all count if you receive them on a predictable schedule.
If you're a retiree or senior who lives on a fixed income, an unexpected bill doesn't wait for your next pension deposit. At iCash, your credit score isn’t the main factor. We look at your regular income and whether the loan fits your budget, and pension income (whether it comes from one source or a few combined) can meet that standard.
This guide is part of our broader look at payday loans with government benefits, and it focuses specifically on pension income for retirees and seniors. It covers what counts as pension income, how much you need, what a loan costs, and how to apply. For CPP-specific numbers and rules, review the sections below.
Key Takeaways

Pension income counts — CPP, OAS, and private or employer pensions can all qualify as verifiable income for a payday loan, on their own or combined, as long as payments are regular.
Flat fee of $14 per $100 borrowed — no hidden charges, subscription fees, or surprise costs. You see the full repayment amount before you accept.
No upper age limit — the only requirement is the standard minimum of 18 (19 in BC, NB, and NS). Retirement doesn't come with an expiry date on eligibility.
Apply online 24/7 — get a quick decision, then funds sent by Interac e-Transfer, typically within minutes of signing your agreement.
Retirement income in Canada comes from more than one source, and most seniors receive a mix of them.
For loan eligibility purposes, three categories qualify:
Canada Pension Plan (CPP), including CPP retirement and CPP disability benefits (for other disability-related income, see our guide to payday loans with disability income)
Old Age Security (OAS), the federal benefit paid to eligible seniors regardless of work history
Private or employer pensions, such as a defined benefit plan, a locked-in retirement account payout, or an annuity from a former employer
You don't need all three types. What matters is that your combined pension income, from one source or several, meets the minimum threshold and arrives on a consistent schedule each month.
iCash looks for a minimum net monthly income of $800, the same threshold used across our government-benefit content. This isn't a promise of approval, but it's the starting point lenders use to check that you can reasonably repay the loan.
For many seniors, CPP and OAS together may be enough to meet this income threshold without needing a private pension as well. When both payments are coming in each month, the combined amount can be well over $800.
Your actual CPP payment depends on factors such as how much and how long you contributed and the age you started receiving your pension, while your OAS amount depends on factors including how long you've lived in Canada after age 18 and the age you began collecting it.
If your CPP or OAS payment isn't enough to meet the lender's income requirement on its own, you may still qualify. A private or workplace pension can also be included when your income is reviewed. For example, if you receive CPP, OAS, and a pension from a former employer, the lender may look at all three payments together rather than expecting one source to meet the requirement.
There's no upper age limit for a pension loan. So yes, you can borrow against your pension in Canada well into your 70s, 80s, or beyond, as long as you meet the standard eligibility rules that apply to every applicant.
The only age requirement is the standard minimum: you need to be 18 years old (19 in British Columbia, New Brunswick, and Nova Scotia). Once you clear that bar, your pension income is treated the same way at 65 as it is at 95. Retirement doesn't come with an expiry date on eligibility.
Every iCash loan costs $14 for every $100 you borrow, regardless of whether your income comes from CPP, OAS, a private pension, or a mix of all three. Your credit history doesn't change this fee either; the rate is the same for every applicant.
Let’s visualize that rate with a few common loan amounts:
Loan Amount | Fee ($14 per $100) | Total Repayment |
$300 | $42 | $342 |
$500 | $70 | $570 |
$1,000 | $140 | $1,140 |
These figures assume a standard repayment term. Use the loan cost calculator to estimate the exact cost for your own loan amount and repayment date, since your actual fee depends on how much you borrow and when you repay it.
Not to iCash. What matters is that your pension income is regular and can be verified in the bank account you apply with. You can combine more than one source, such as OAS plus a workplace pension, to reach the $800 minimum.
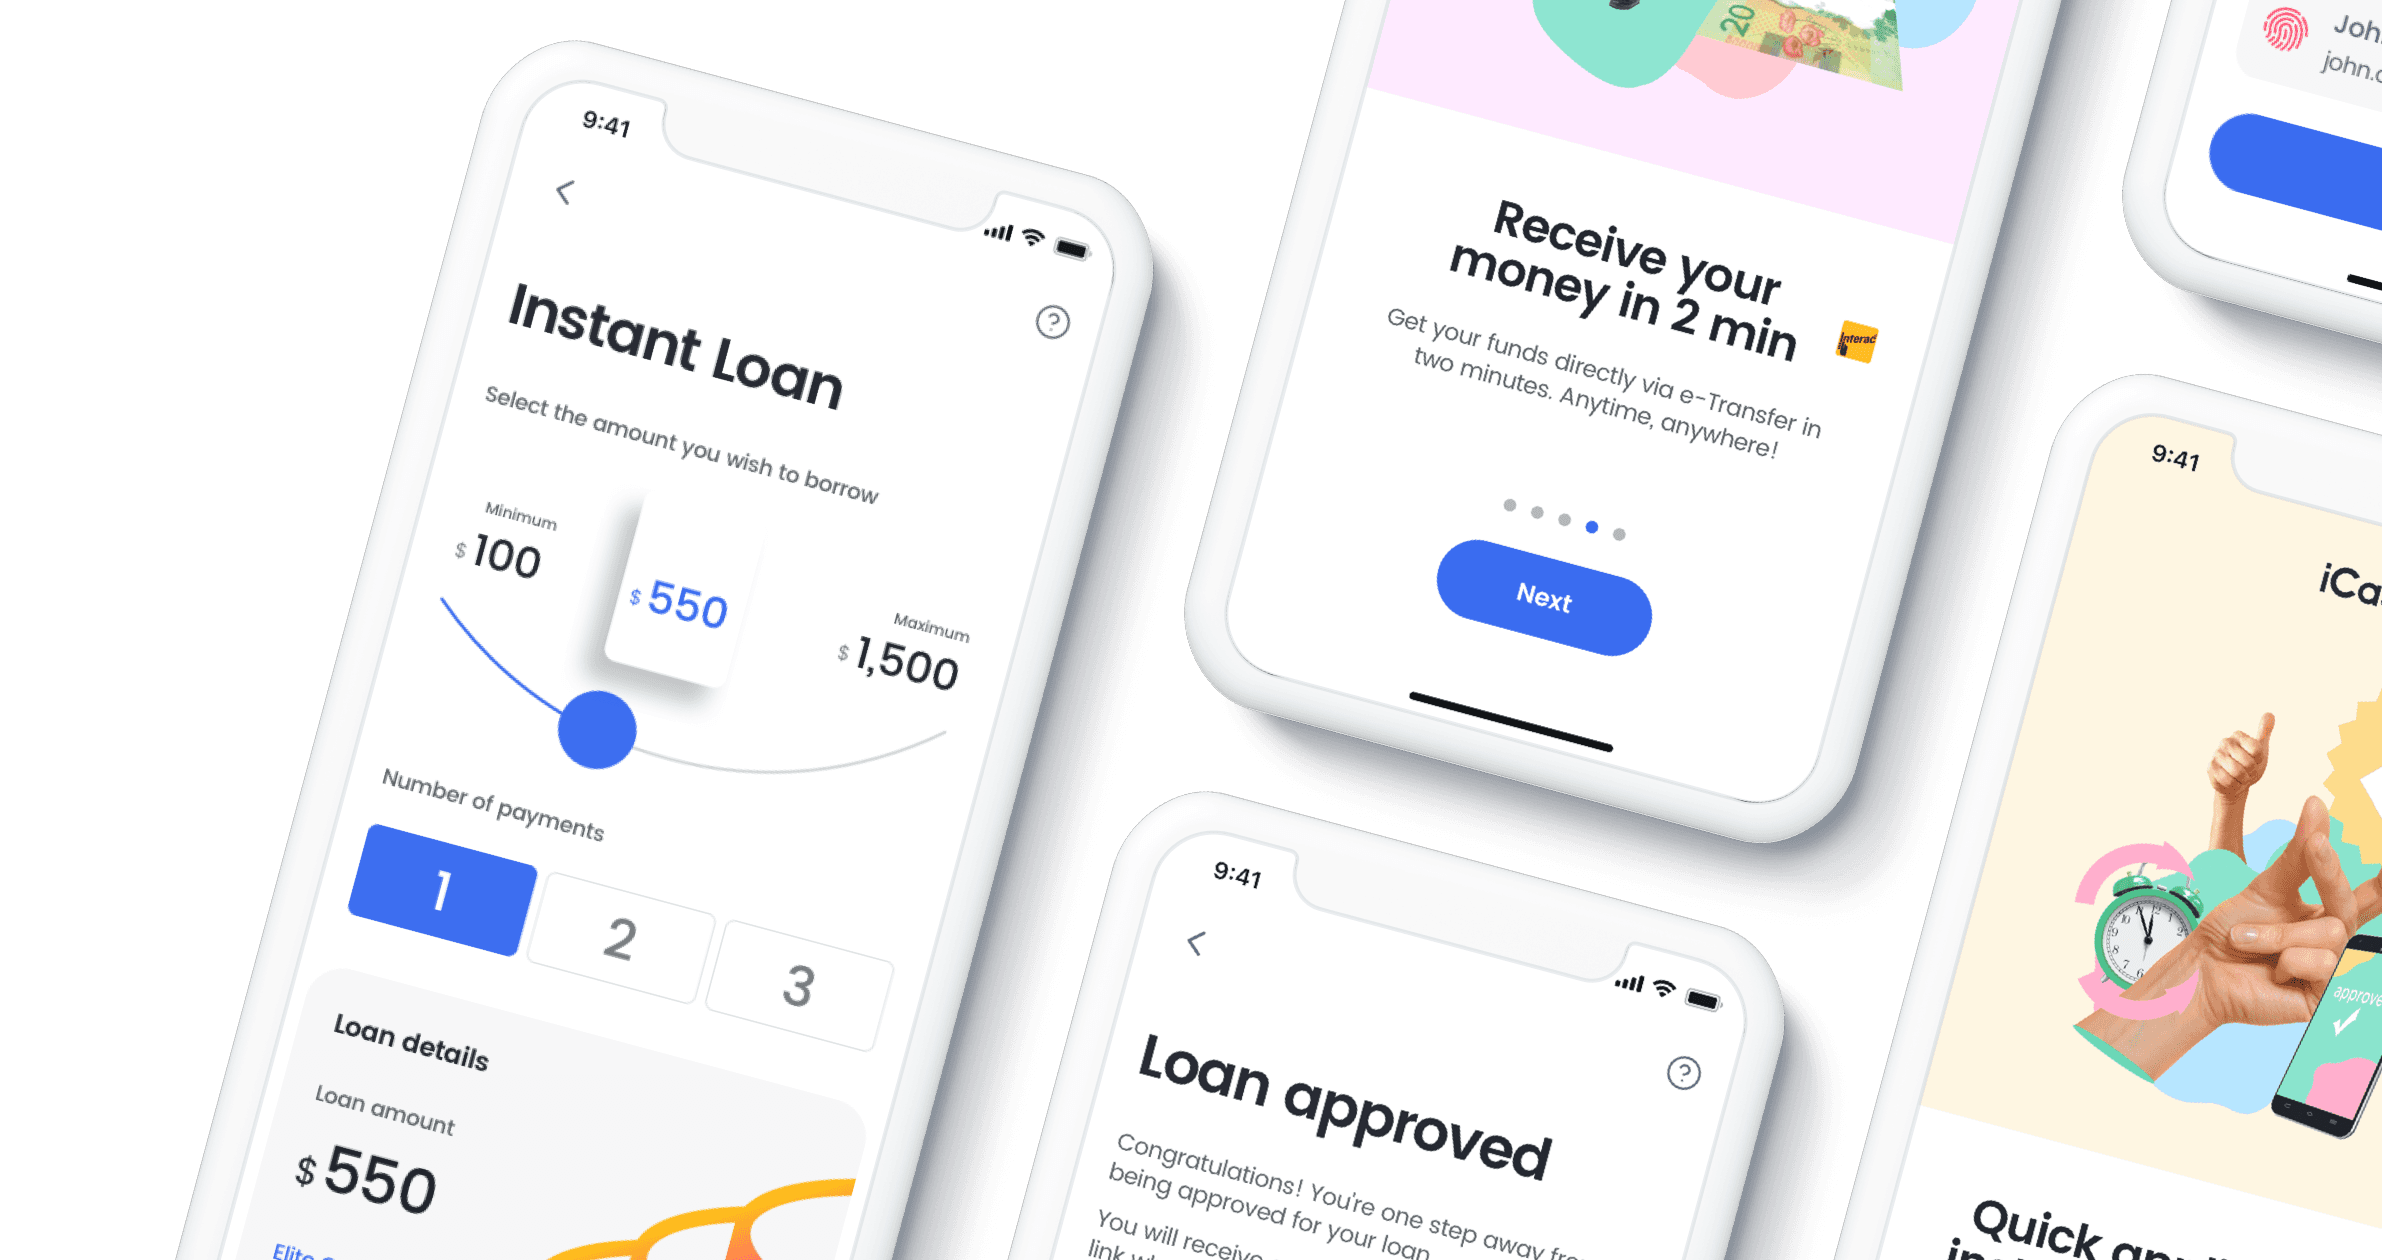
A pension loan application takes three steps, the same process iCash uses across every loan type we offer.
Apply online: Fill out the form with your pension income, banking details, and the loan amount you need. It takes a few minutes from your phone or computer.
Get an instant decision: iCash reviews your application right away, so you get an answer without a days-long back-and-forth.
Receive your funds by Interac e-Transfer in 2 minutes: Once you sign your agreement, the money lands in your account, even on evenings, weekends, or holidays.
See how funds are received for more detail on the Interac e-Transfer process, including what to do if your bank hasn't set up Autodeposit yet.
Short-term borrowing can have a place in a pensioner's budget when the problem is timing rather than a permanent lack of income.
For example, your car could need a $500 repair today while your next pension deposit is still two weeks away. You might have an unusually large utility bill due before your CPP or OAS arrives, or an unexpected expense may come up that you can't put off until your next payment.
In a situation like that, a pension loan can bridge the period between the expense and your next deposit. Before applying, though, look beyond whether you can technically repay the loan. Think about what will be left from your next pension payment afterward. You still need enough to cover groceries, housing, utilities, transportation, and your other regular bills.
If borrowing has become a monthly habit, a payday loan won’t fix it. It only spends part of your next payment early, plus a fee. Look for help with the ongoing shortfall instead:
Check that you receive every federal and provincial benefit you qualify for, such as Ontario’s GAINS
or the Alberta Seniors Benefit
Ask a local credit union about lower-cost borrowing.
Talk to a free, non-profit credit counsellor
iCash asks every applicant to borrow responsibly and to take on only what fits comfortably within your next pension cycle. A short-term loan should solve a short-term problem, not create a longer one.
Behind each review is an experience that matters
Since 2016, we've helped over 1.6 millions Canadians get instant loans online.
Since 2016, we've helped over 1.6 millions Canadians get instant loans online.
Read more reviews.
We help our members
get their finances
back on track
Have more questions? Check out our full FAQ.